Wise in Argentina: Does It Work, and What to Use Instead (2026)
Wise works in Argentina as a personal account: USD details, pesos to a CBU up to USD 18,000 a month. What it costs, what residents can't do, the BCRA 20-day rule, and what to use instead.
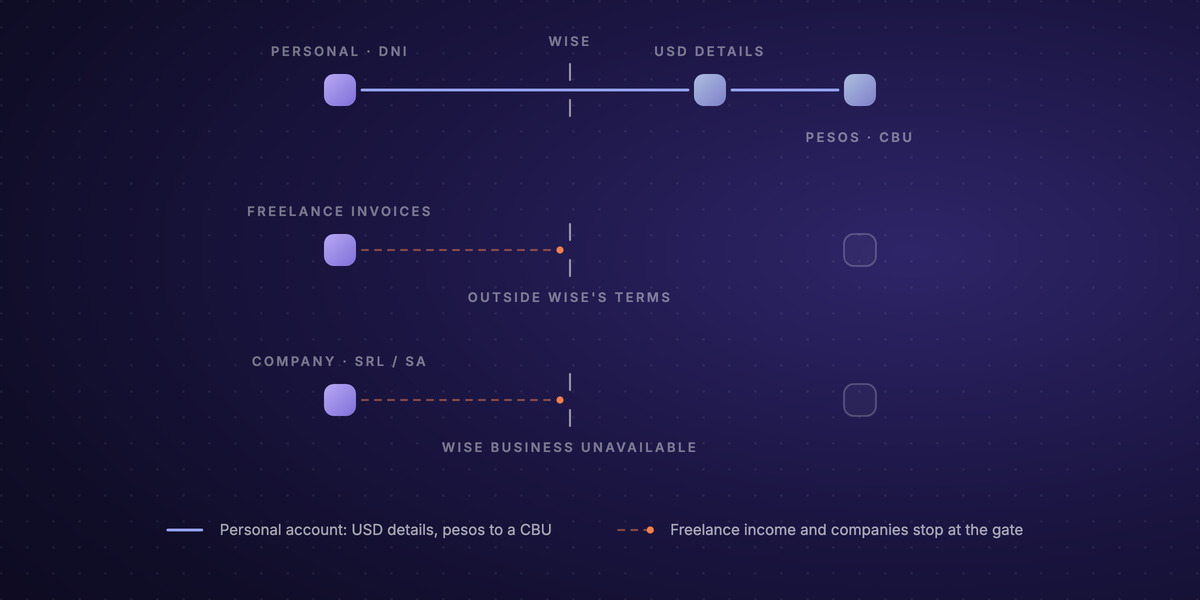
Yes, Wise works in Argentina, but only as a personal account. You open it online with your DNI, get account details in US dollars, euros and pounds, receive money through them for free, and send it home as pesos to any bank account with a CBU, up to the equivalent of USD 18,000 a month. What you can't get is everything around that: Wise Business is unavailable to Argentine companies, there's no Wise card for residents, and you can't top up from an Argentine card.
That last group of gaps decides who Wise is for. For money from family abroad, a refund, savings in another currency, it does the job well. For getting paid by clients, it runs into a wall that most Argentine guides skip: Wise's own terms reserve the personal account for personal transactions and send freelancers and sole traders to Wise Business, which doesn't open from Argentina. Below is what Wise is, what it costs an Argentine resident today, the central-bank rule that applies to any balance you keep abroad, and what to use if you're invoicing for a living.
What is Wise?
Wise is a UK-founded payments company, not a bank. The group, Wise Group plc, has traded on Nasdaq since May 2026 and keeps a secondary listing in London. It's regulated as an e-money institution (by the FCA in the UK and FinCEN in the US, among others), and it built its name on two things: converting currencies at the mid-market rate with a visible fee, and giving people local account details in other countries, so a US client can pay you by ACH as if you lived in Ohio.
Because Wise isn't a bank, your balance isn't a deposit. Wise keeps customer money separate from its own, in bank accounts and short-term government bonds, but it isn't covered by deposit insurance schemes like the UK's FSCS or the US FDIC.
Does Wise work in Argentina? What residents can and can't do
| What you want | Works for an Argentine resident? |
|---|---|
| Open a personal account with your DNI | Yes, online, with a selfie and document check |
| USD, EUR and GBP account details to receive payments | Yes, free to receive through them |
| Hold a balance in dollars and 40+ other currencies | Yes |
| Send pesos to an Argentine bank account (CBU) | Yes, up to USD 18,000 equivalent per calendar month |
| Send pesos to a virtual wallet (CVU: Mercado Pago, Ualá and the like) | No, CBU only |
| Send dollars to your Argentine dollar account | Wise lists Argentina for USD over Swift, but its Argentine guides only describe the peso route: confirm in the app |
| Wise debit card | No, not issued to Argentine residents |
| Top up with an Argentine card | No |
| Interest or stocks on your balance | No |
| Wise Business for a company (SRL, SA) | No, unavailable in Argentina |
Two practical notes from the onboarding. Wise asks every customer for a tax self-certification, so have your CUIL or CUIT handy. And Wise's own Argentine guide mentions a first top-up of about USD 20 from a payment method in your name to activate your account details; since Argentine cards don't work, that usually means a transfer from an account abroad.
What Wise costs in Argentina
Receiving is the cheap part. Payments into your USD, EUR or GBP details over local rails (ACH in the US, SEPA in Europe) cost nothing. A dollar wire over Swift costs USD 6.11 to receive.
Getting the money home is where you pay. Wise converts at the mid-market rate, which is not the official dollar or the MEP rate, and charges a small fixed fee plus a percentage. On 12 October 2026, sending 1,000 dollars from a Wise balance to an Argentine bank account in pesos cost USD 21.01 in fees, about 2.1%, and delivered ARS 1,484,883. The rate and the fee move daily, so check Wise's calculator on the day you send. Pesos usually land one working day after the conversion, and the conversion itself can take up to two.
The limits to plan around:
- USD 18,000 a month in pesos to Argentine accounts. A bigger month has to wait or go another way.
- CBU only. A CVU from Mercado Pago or another wallet won't work as a destination.
- One direction. You can't send pesos into Wise or top up an ARS balance from outside; pesos only come out.
The 20-business-day rule for money held abroad
Argentina lifted its currency controls for individuals in April 2025, and since September 2025 there's no cap on how much service-export income you can collect. One rule survived. Under the central bank's current text (Communication "A" 8481, September 2026), payment for services you sell abroad has to be brought into Argentina within 20 business days of landing in an account abroad. You don't have to sell the dollars: an individual can credit them to their own dollar account at an Argentine bank and keep them there.
A Wise balance is an account abroad. So if client payments sit there, the clock is running. Our reading of the rule, not legal advice: if your Wise balance is service income, plan to move it within the 20 days, and check your case with an accountant.
Two tax points follow from the same fact. Balances abroad count for Bienes Personales, so declare them. And Argentina has signed the OECD's updated reporting standard that extends to e-money accounts like Wise, with information exchange expected to start in 2027 on 2026 data: assume ARCA will see the account.
The freelancer problem: personal account, business money
This is the gap that decides the question for anyone invoicing clients. Wise says personal accounts are for personal transactions only, that using one for business breaks its terms of use, and that freelancers and sole traders should use Wise Business. From Argentina, Wise Business isn't available, whether you're a monotributista or an SRL.
Many Argentine freelancers use the personal account anyway. But "outside the provider's terms" is a poor foundation for the account your income depends on, and a company can't use Wise at all. If you invoice for a living, you want a route that's built for business payments and works from Argentina.
What to use instead of Wise in Argentina
Your options depend on who you are:
- Bank wire to your own dollar account. Since September 2025 your Argentine bank can't charge its own fee for crediting service-export dollars; only documented correspondent-bank costs pass through. Slow (Swift), but fully inside the rules, and the dollars are already home.
- Payoneer. Built for marketplace and platform payouts: Upwork, Fiverr and the like pay into it directly. Receiving by ACH costs 1%, and Payoneer withdraws to Argentine bank accounts in pesos or dollars for up to 2%. There's an annual fee of USD 29.95 if you receive less than USD 6,000 in 12 months.
- An account built for income from companies, for freelancers too. That's what we built at Localbridge, and it's the one block in this article about us.
Localbridge covers exactly the case Wise leaves out. A company opens a business account; a freelancer opens an individual one, and the individual account is made for income from companies: client invoices, salary from an employer abroad, marketplace and platform payouts. What it doesn't take is transfers from other individuals, so money from family stays Wise's job. Either way, a virtual account gives you local payment details in USD, EUR, GBP, MXN, BRL and COP: your US client pays by ACH, your European one by SEPA. Each incoming payment converts automatically into USDC or USDT, digital dollars you can keep, send to suppliers' bank accounts in the supported currencies, or move to your own wallet. One honest limit: we don't pay out Argentine pesos today, so for pesos you sell your stablecoins on a local exchange, a routine step in Argentina. And the 20-day rule above is about where money sits, not which app holds it, so plan the transfer home either way. Localbridge itself never holds your funds: accounts and conversion run on Bridge, a Stripe company, and custodial wallets, where offered, are held by Bridge. Fees are on the pricing page.
For every route side by side, with costs and timings, see our guide to receiving payments from abroad in Argentina, and for the head-to-head of the two best-known platforms, Payoneer vs Wise.
FAQ
Can I open a Wise account in Argentina? Yes, a personal one. You sign up online with your DNI or passport and a selfie check; there's no opening or monthly fee. A business account isn't possible: Wise Business is unavailable to companies registered in Argentina.
Can I withdraw money from Wise to an Argentine bank? Yes, in pesos, to any account with a CBU, up to the equivalent of USD 18,000 per calendar month. Wise converts at the mid-market rate plus its fee, and the pesos usually arrive within one to three working days. Virtual wallets with a CVU aren't supported.
Does Wise give Argentines a card? No. The Wise card isn't issued to Argentine residents, and you can't top up your account with an Argentine card either.
Can I receive my freelance income in Wise from Argentina? Technically the money arrives, but Wise's terms reserve personal accounts for personal transactions and direct freelancers to Wise Business, which isn't available in Argentina. If client income is your main use, pick a provider built for business payments.
Is Wise legal in Argentina? Using Wise is legal, and since 2025 individuals face no currency controls. The obligations are yours: declare the income and the balance abroad, and bring service-export proceeds into Argentina within 20 business days under the central bank's rules.
What exchange rate does Wise use for pesos? The mid-market rate, which is neither the official BCRA rate nor the MEP dollar, with Wise's fee shown separately. On 12 October 2026 that meant about 2.1% in fees on a 1,000-dollar transfer.